See also: InstaSpot trading indicators for NASDAQ 100 (NDX)
After Tuesday's ADP release and the PCE print, the NASDAQ 100 trades near 30,460 on Wednesday as it attempts to build on a recovery sparked by softer-than-expected PCE inflation. That print cooled odds of an October Fed hike and supported risk assets, but a resilient labor market and Friday's payrolls report keep traders cautious.
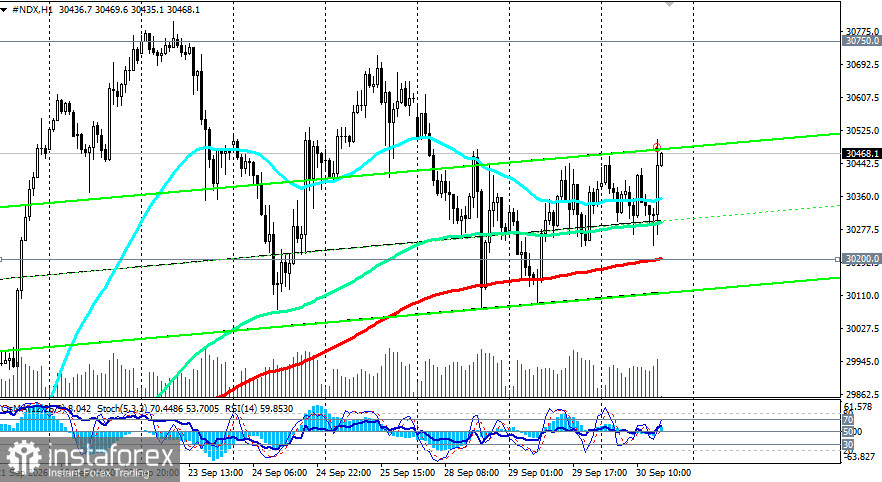
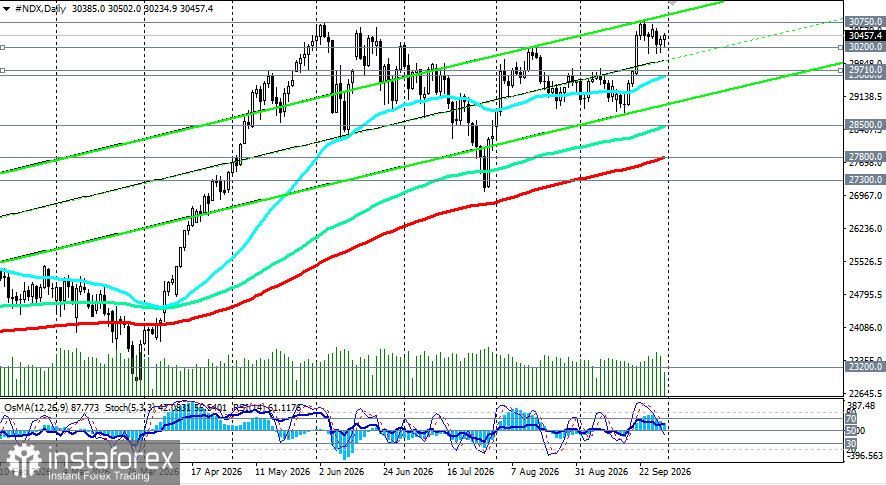
The technical picture remains neutral-bullish: the index is range-bound, and indicators point to insufficient momentum for a decisive breakout higher.
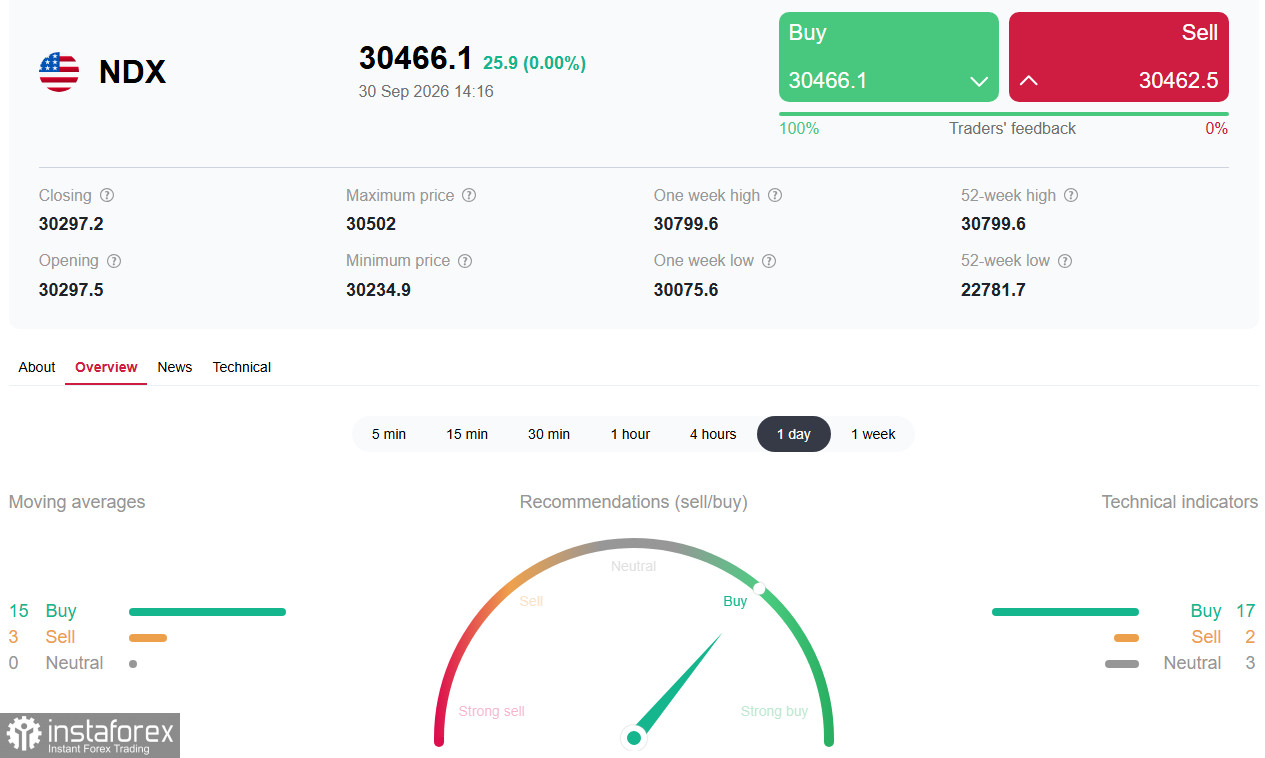
InstaSpot aggregated technical analysis issues a "Buy" signal on the daily chart: 17 of 22 applied indicators favor long positions.
Indicators and moving averages:
Key levels:
Resistance: 30,750 (upper boundary of the 30,000–30,750 range and record-high zone).
Support: 30,200 (200-EMA on H1), 30,000 (psychological level), 29,710 (200-EMA on H4), 29,600 (50-EMA on D1), 29,000 (round level), 28,500 (144-EMA on D1).
The index is stuck in a 750-point range between 30,000 and 30,750, roughly 50% complete. The "no-trade zone" is 30,500–30,800, where most trades are better avoided until a decisive breakout.
The main question this week is whether the NASDAQ 100 can hold above 30,000 ahead of the jobs report. If that support holds, a breakout to 31,100 is possible. If NFP prints strong and yields continue to rise, the index may test 30,200 (200-EMA on H1) and below.
The ISM Manufacturing PMI for the US is scheduled for Thursday, October 1, at 12:30 GMT. The prior reading was 54.6, and the prices-paid index printed 71.1, near a four-year high. Strong data would confirm economic resilience and could revive the odds of an October rate hike.
Also on Thursday, several Fed speakers will present and could provide new clues on the policy path. After the softer PCE print, the market will seek confirmation that the Fed could still pause in October.
On Friday, October 2, at 12:30 GMT, the US nonfarm payrolls (NFP) report for September is due. Consensus forecasts roughly 90k new jobs versus 162k in August, with the unemployment rate likely around 4.1%. This is the key trigger to determine the index's direction for the coming weeks.
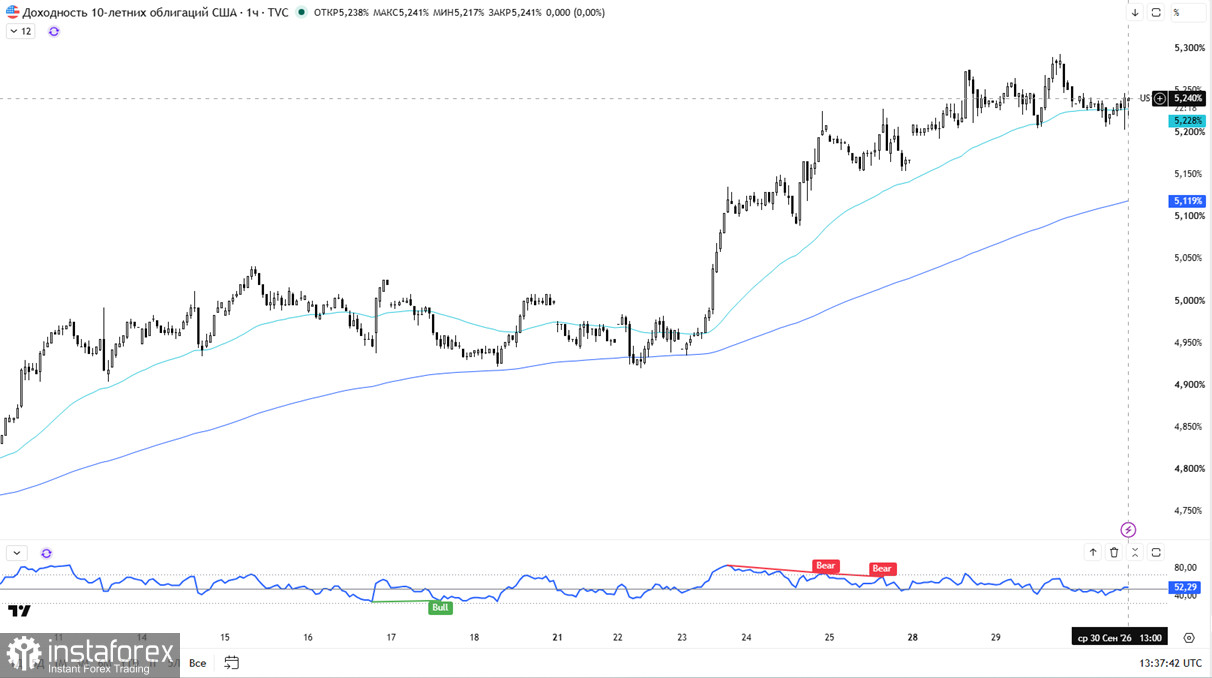
Separately, watch Treasury yields. The 10-year is holding near 5.24–5.26% — a 2007 high — and the 30-year around 5.57%, a level not seen since 2002. If yields rise further following strong jobs data, tech shares will come under pressure.
The NASDAQ 100 is consolidating in the 30,000–30,800 band, supported by softer PCE inflation but constrained by strong employment data and high rates. The key level for bulls is 30,800; for bears, it is 30,000.
For short-term traders:
For medium-term investors:
This overview was prepared using public sources and media reports and represents a price action analysis that depends on many factors. Therefore, risk management and position monitoring are crucial.
See also our other market reviews:
GBP/USD: a bounce to 1.3300, but a hawkish Fed does not let markets relax
*La presente analisi del mercato ha un carattere esclusivamente informativo e non rappresenta una guida per l`effettuazione di una transazione.
Le recensioni analitiche di InstaSpot ti renderanno pienamente consapevole delle tendenze del mercato! Essendo un cliente InstaSpot, ti viene fornito un gran numero di servizi gratuiti per il trading efficiente.