

Nella nostra squadra ci sono più di 7.000.000 trader! Ogni giorno ci impegniamo a far sì che il trading migliori. Conseguiamo grandi risultati e ci muoviamo in avanti.
Il riconoscimento da parte di milioni di trader in tutto il mondo rappresenta l'alta valutazione della nostra attività! Voi avete fatto la vostra scelta e noi faremo la nostra al fine di soddisfare le vostre aspettative!
Assieme siamo una grande squadra!
InstaSpot. Siamo orgogliosi di lavorare per voi!



Attore, campione del mondo di lotta libera e semplicemente un vero maciste russo! Persona venuta dal nulla. Persona che rispecchia i nostri obiettivi. Il segreto del successo di Taktarov consiste nel mirare continuamente al suo scopo.
Dischiudi anche tu tutti gli aspetti del tuo talento! Impara, prova, sbaglia, ma non fermarti!
InstaSpot - la storia delle tue vittorie inizia qui!

The September producer-price release — up 6.8% year-on-year — may seem to signal a slowdown in inflationary pressure along production chains (consensus was 7.6%). However, import prices in yen soared 24.5% year-on-year, while costs for chemicals, plastics and non-ferrous metals rose 13.3%, 12.8% and 40.2% respectively. That means yen weakness, combined with persistent geopolitical tension in the Middle East, continues to transmit external cost pressures into the Japanese economy with growing force; the moderation in headline PPI only masks this structural process. Economists surveyed by Reuters explicitly noted that producer prices "support the Bank of Japan's intention to raise rates in due course," despite no urgency for an immediate hike.
Japanese crude-oil imports in June rose to 8.6 million tonnes, exceeding last year's level for the first time in four months. Shipments from the United States drove the recovery, doubling from May to 2.7 million tonnes—almost one-third of total imports. Japan's dependence on the Middle East fell from 94% in 2025 to 62.3% by June.
US crude, however, costs Japan roughly 15% more — a gap driven by higher shale-oil production costs and logistics. Moreover, Japanese refineries have historically been optimized for the heavier Middle Eastern crudes; switching to lighter US grades requires additional capital expenditure to reconfigure processes. From a supply-availability standpoint, there is no immediate threat of disruptions. But if the Strait of Hormuz remains effectively closed for a prolonged period and oil prices stay at current levels, Japan would face a compounding set of shocks.
Higher energy import costs worsen the terms of trade and directly reduce real national income. If oil stays above $100/bbl and import prices in yen keep rising, the current-account deficit could widen to levels not seen since the first oil shock — putting fundamental downward pressure on the yen as financing the deficit requires steady inflows of foreign capital.
A second channel is through real household incomes. Rising energy and food prices have already contributed to stagnation in private consumption. If high prices persist, real incomes will keep shrinking, further depressing consumption and GDP growth.
A third channel is via corporate investment. Uncertainty about future energy prices and supply reliability encourages companies to delay capex.
A fourth channel is via inflation expectations. If elevated energy costs persist, the BOJ may be forced to raise rates more aggressively than domestic conditions alone would justify. That could trigger a sharp economic slowdown and weaken the yen as markets price in a recessionary scenario.
The market still expects the BOJ rate to be 1.25% in December as the base case. However, if the energy shock is prolonged, USD/JPY should remain volatile, the policy-rate differential will stay large, and even a December BOJ move would not fully eliminate that gap.
Speculative positioning shows a yen short bias of +$4.93 billion for the reporting week — a sizable overweight — yet the implied price has no clear trend and has reverted to the long-term mean.
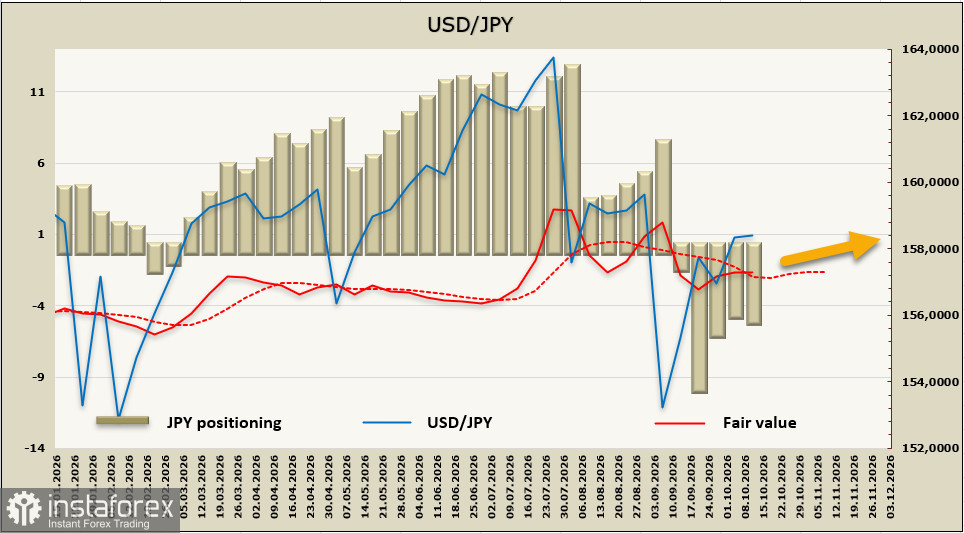
USD/JPY has returned to the middle of the wide range that dominated 2026, and the near-term direction is unclear. In the previous note, we suggested the pair would remain within 157–160 absent a clear driver; little has changed over the past week. Resistance sits at 160.35; while the pair remains below that level, the probability of renewed downside appears higher than a resumption of the uptrend.
*La presente analisi del mercato ha un carattere esclusivamente informativo e non rappresenta una guida per l`effettuazione di una transazione.
Le recensioni analitiche di InstaSpot ti renderanno pienamente consapevole delle tendenze del mercato! Essendo un cliente InstaSpot, ti viene fornito un gran numero di servizi gratuiti per il trading efficiente.


